Softcat's $1.05bn acquisition of GDT
Hussain Jeddy · 18 September 2026
Share on LinkedInOn 17 September 2026, Softcat plc, the London-listed IT infrastructure and services reseller, announced it had agreed to acquire GDT, a Dallas-headquartered enterprise IT solutions provider currently owned by US private equity firm H.I.G. Capital, for an enterprise value of $1,050 million (£785 million). The price is calculated on a cash-free, debt-free basis (a standard way of pricing a private company sale so the buyer pays only for the operating business, adjusting separately for however much cash or debt happens to be sitting on the target's balance sheet at completion), and is subject to a normal working-capital adjustment.
The Parties
Softcat is a FTSE 250-listed UK company that sells and manages IT infrastructure, software and services, or simply sort of a specialist middleman helping businesses buy, configure and run their networking, cloud, data centre and cybersecurity kit, rather than a maker of that kit itself. GDT, founded in 1996 and headquartered in Dallas, Texas, does a similar job for US customers: it designs, builds and supports enterprise IT infrastructure across networking, hybrid cloud/data centre, cybersecurity and collaboration technology, with a particular focus on large, complex, multinational clients. H.I.G. Capital, a private equity firm, has owned GDT since making a growth investment in the business in December 2021.
Structure & Process
This is a private acquisition, GDT is privately held, so there is no public takeover bid, scheme of arrangement or stock-exchange rulebook involved, unlike most of the UK-listed deals this newsletter usually covers. Instead it is a straightforward negotiated purchase of the entire equity of a US business (structured through its holding entity, GDT Topco, L.P.) via a definitive agreement between Softcat, H.I.G. Capital and GDT. Because the transaction is likely to meet US antitrust filing thresholds, it will most likely require clearance under the Hart-Scott-Rodino Act (the US pre-merger antitrust notification regime) before it can close, though neither company's announcement explicitly confirms an HSR filing, so this should be read as a reasonable inference rather than a confirmed fact. Both companies' announcements refer only to "customary closing conditions."
The Financing Angle
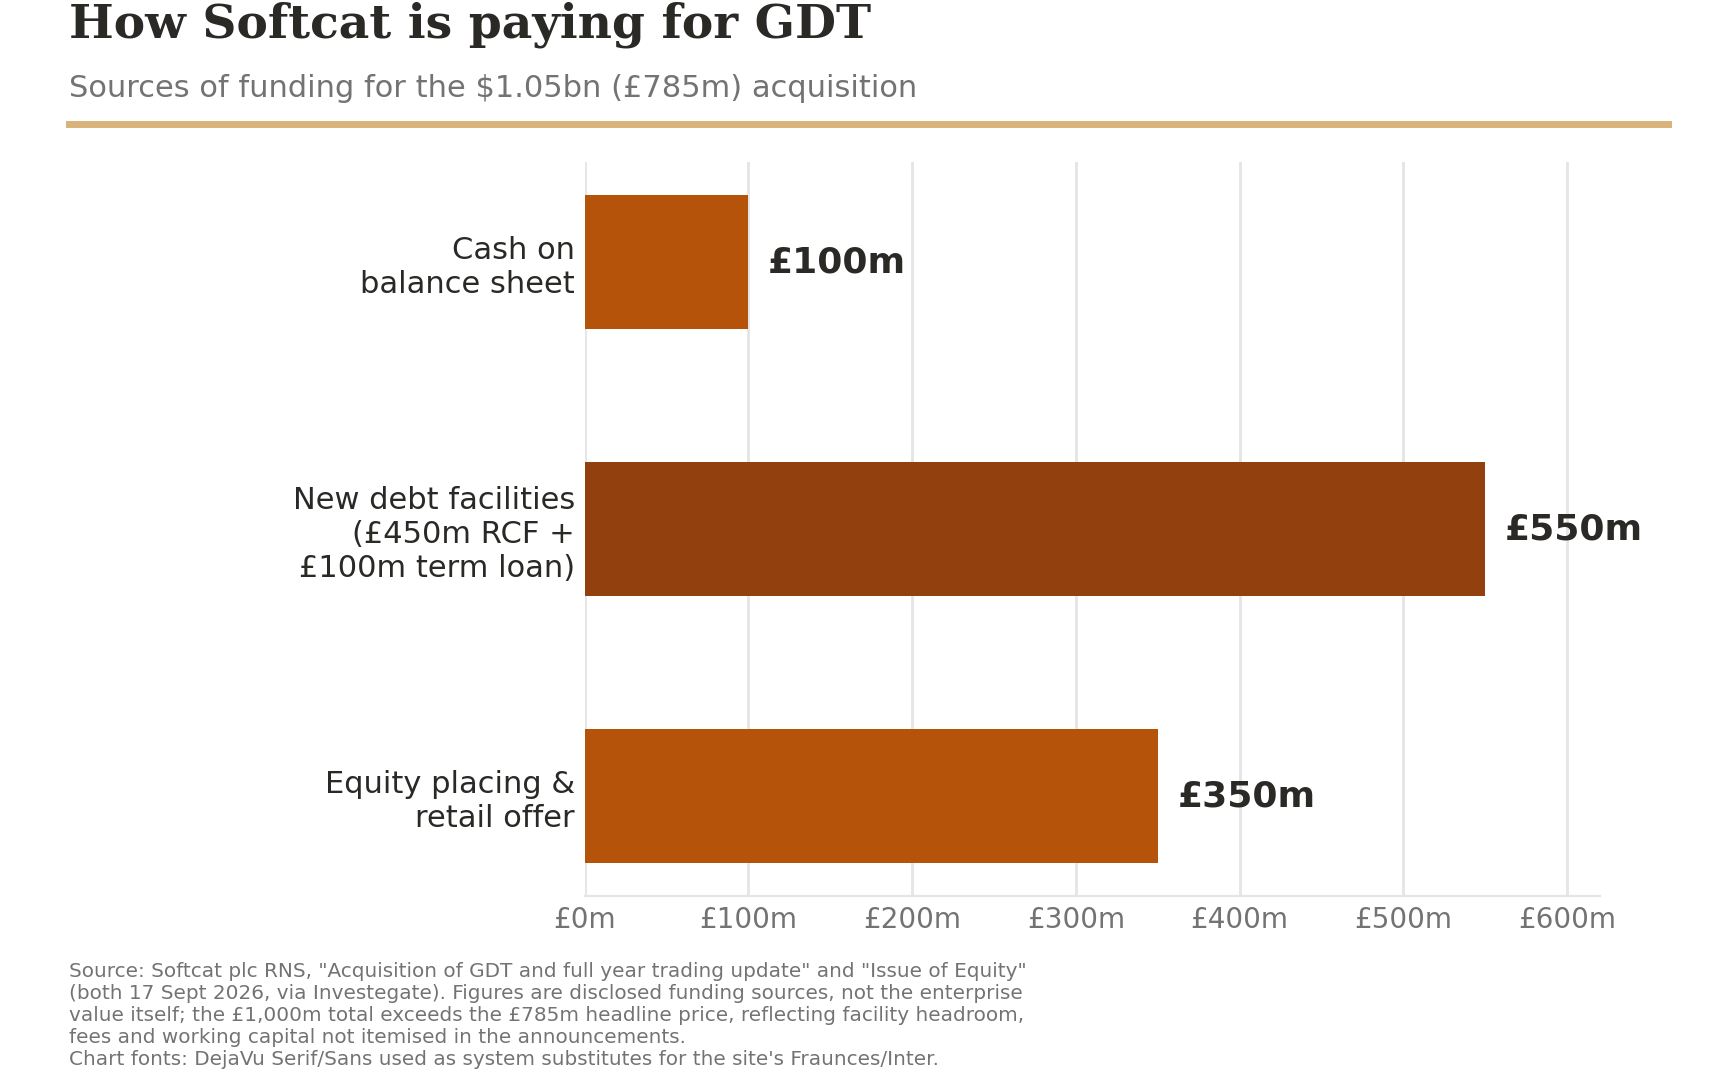
Softcat is funding the $1.05bn price from three sources: about £100m of cash already on its balance sheet; £550m of new debt (a £450m revolving credit facility plus a £100m term loan) arranged with relationship lenders JPMorgan Chase Bank, Barclays Bank and BNP Paribas; and a £350m equity placing and retail share offer, with J.P. Morgan Securities, Peel Hunt and BNP Paribas acting as joint bookrunners. The equity raise is expected to represent under 10% of Softcat's existing issued share capital. Softcat says the deal will leave it with estimated net debt leverage (a measure of how many years of core earnings it would take to pay off net debt) of around 1.3x at completion, falling to below 1.0x by July 2028, within its own target range of 0.5–1.0x. On the sell side, Guggenheim Securities and Moelis & Company advised H.I.G. Capital and GDT.
Kirkland & Ellis LLP is confirmed as legal counsel to H.I.G. Capital and GDT on this transaction.
Why it Matters
For Softcat, this is a significant, US-market-opening deal: it roughly doubles down on a strategy of pushing beyond its traditional UK/European reseller base into large-scale US enterprise IT services, an area increasingly driven by demand for AI infrastructure, networking and data-centre capacity. It is also a fairly rare example of a UK-listed mid-cap funding a nine-figure-dollar US acquisition partly through a public equity raise (rather than debt alone), which is itself a signal of how confident Softcat's board is in the growth case. For private equity, it is another data point in H.I.G. Capital's playbook of buying, building and then selling mid-market IT services platforms, GDT is expected to deliver around $240m of gross profit and $80m of EBITDA for the twelve months to December 2026, at roughly 30% year-on-year growth, which gives some sense of why H.I.G. is exiting now rather than holding longer.
Real-World Impact
If you've ever wondered who actually sets up the servers, cybersecurity systems and cloud infrastructure that big companies (and increasingly, AI systems) run on, this is that industry. GDT's roughly 30% annual growth is itself a small window into just how much money large companies are pouring into AI-ready data centres and networking right now, this deal is really a bet that trend keeps going. Both companies say GDT will keep its name, its leadership team and its workforce after the deal closes, so there's no confirmed job risk from this specific transaction, though as with any acquisition, some overlap or restructuring further down the line is not something either company has ruled out, it's simply not been announced. For UK readers, it's a reminder that "British company" doesn't mean "UK-only business": Softcat funding roughly a third of a $1.05bn US deal through a stock market share sale is Softcat effectively asking its existing shareholders (and some new retail investors, via the RetailBook offer) to bankroll its American expansion, a bet that, if it pays off, could make Softcat meaningfully less UK-dependent as a business over time. There's no specific antitrust or political controversy attached to this one so far as it's a fairly clean, uncontested industry consolidation story.