Epiris's ~£1.02bn recommended cash offer for Gamma Communications plc
Hussain Jeddy · 7 September 2026
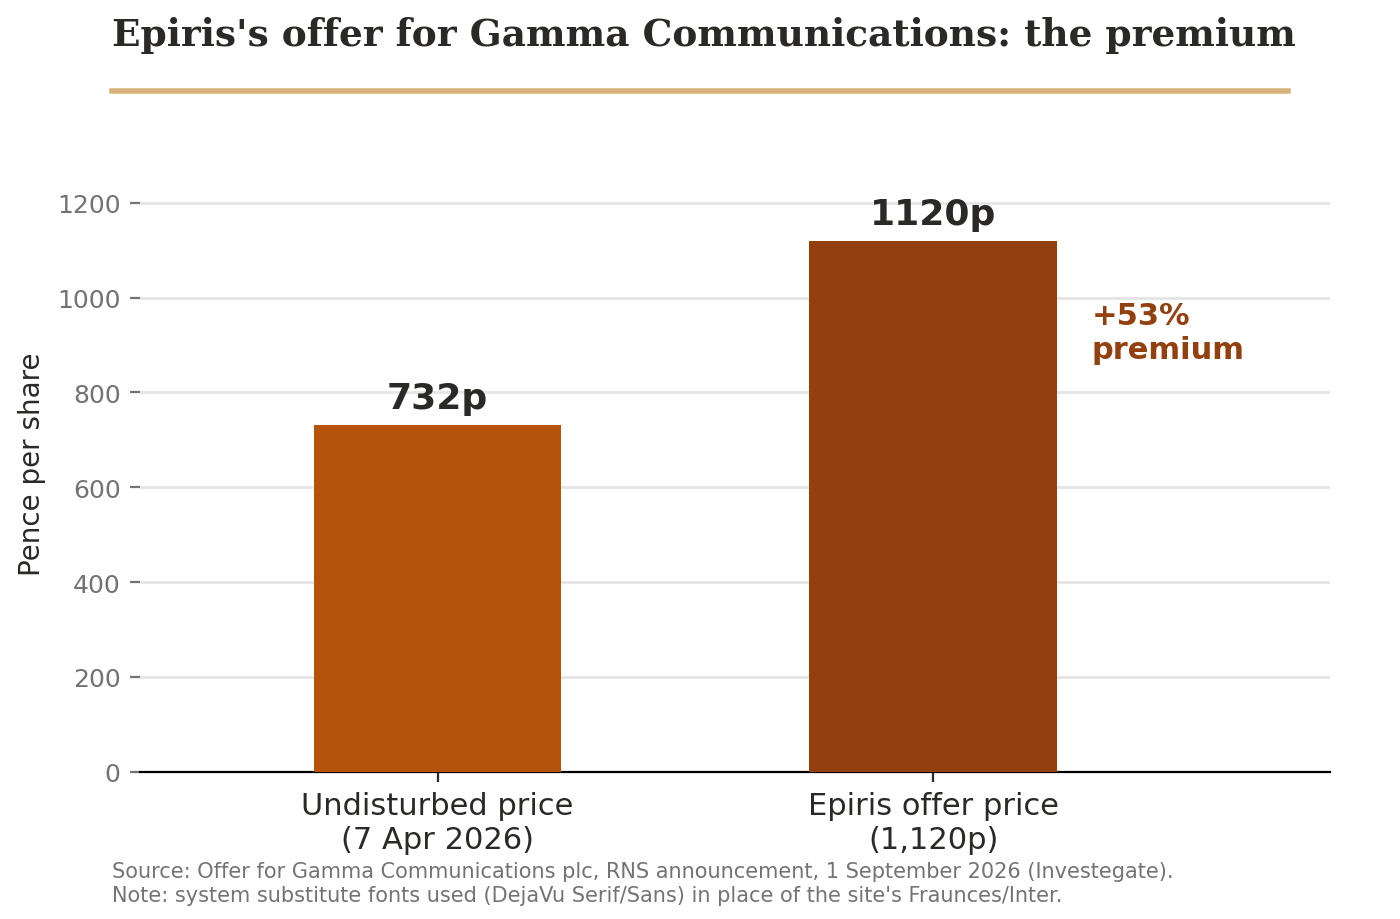
Share on LinkedInGamma Communications plc, the London-listed communications software business, has agreed to be taken private by Bradbury BidCo Limited, a vehicle controlled by funds managed by UK private equity firm Epiris, in an all-cash deal announced on 1 September 2026. Gamma shareholders will receive 1,120 pence per share, valuing the company's fully diluted share capital at approximately £1,015 million (an implied enterprise value, including debt, of about £1,079 million). This is a 53% premium to Gamma's share price the day before the sale process became public. The deal is not yet done, though, as rival private equity firm, Waterland, is weighing whether to come back with a higher bid before a mid-September bid.
The Parties
Gamma Communications plc is a UK-headquartered provider of business communications technology. In practice, this means it sells cloud-based phone systems, video/chat platforms, mobile, business connectivity and cyber security tools that small and large companies actually use to run their internal and customer-facing communications, including voice-enabling of Microsoft Teams. It operates in the UK, Netherlands, Spain, and Germany, split between a 'Gamma Business' division serving smaller companies, often through channel partners and resellers, and a 'Gamma Enterprise' division serving larger organisations directly. Founded in 2001 by Corbishley and Paul Banner, originally to buy up the assets of distressed telecoms businesses, it reported revenue of £645.8 million and adjusted EBITDA of £141.7 million for its 2025 financial year. It is led by CEO Andrew Belshaw and chaired by Martin Hellawell, former long-serving CEO of Softcat.
Epiris LLP is an independent UK private equity firm, formerly known as Electra Partners, tracing its roots back to 1976 and managing more than £2.75 billion of capital. Its existing and past portfolio spans professional audio equipment (Audiotonix), B2B information services (Delinian, formerly part of Euromoney), hospitality (the Big Table Group, which owns Bella Italia and Las Iguanas) and direct cremation services (Pure Cremation), a generalist buyout investor and not a specialist in telecoms or software.
Structure & Process
The Acquisition is intended to be implemented by a scheme of arrangement (a court-supervised procedure under Part 26 of the Companies Act 2006, commonly used for recommended UK public takeovers, requiring approval by a majority in number representing 75% in value of shareholders voting, followed by sanction from the English court), though Bidco has reserved the right to switch to a contractual takeover instead, with the Takeover Panel's consent, if needed.
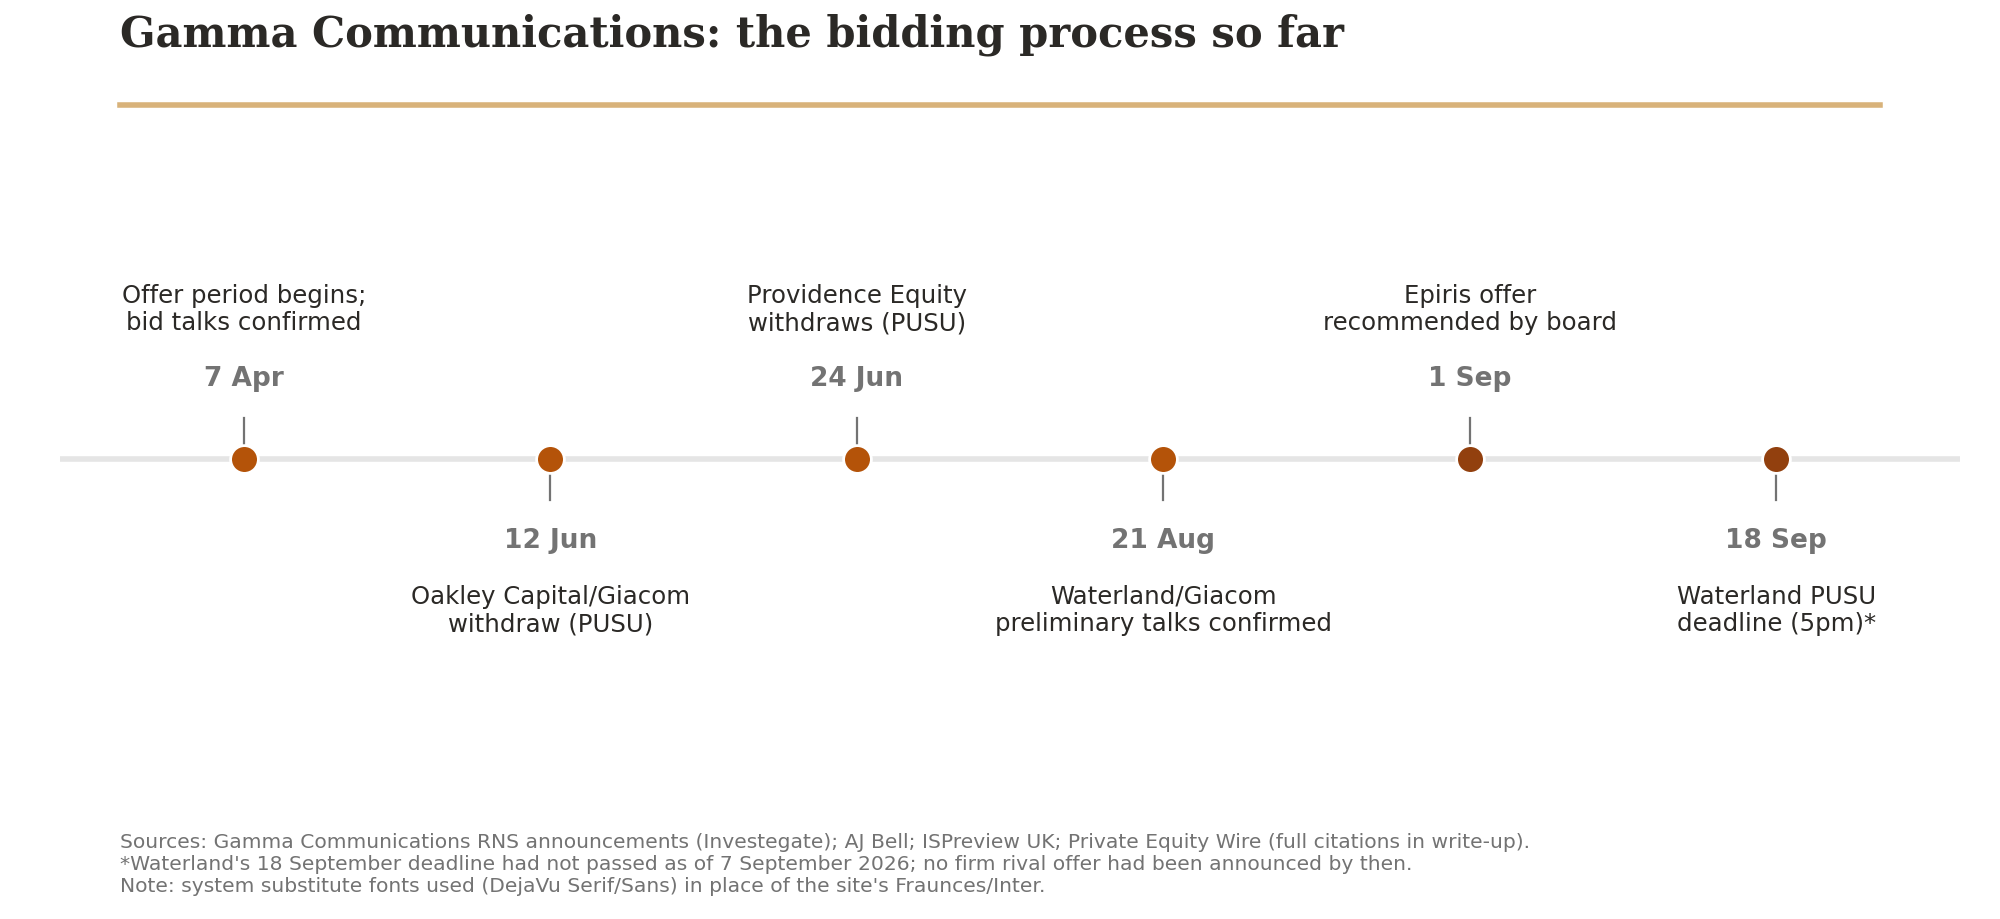
This recommended offer is the outcome of a long and genuinely competitive process, and not a quiet bilateral deal. Gamma entered a formal offer period (the period during which a company is 'in play' under the UK Takeover Code, triggering disclosure obligations) on 7 April 2026, and by May had confirmed preliminary talks with three separate potential bidders. These included US firm Providence Equity Partners, Epiris, and a consortium of Oakley Capital and telecoms reseller Giacom. Under the Code's "put up or shut up" (PUSU) rule (a deadline by which a potential bidder must either announce a firm intention to bid or walk away), Providence withdrew on 24 June 2026 and Oakley Capital withdrew on 12 June 2026, apparently leaving Epiris as the last bidder standing, thus culminating in the 1 September recommended offer.
However, the story isn't fully resolved. Separately, Gamma confirmed on 21 August 2026 that Waterland Private Equity Investments B.V. was also in preliminary talks over a possible offer, with the Giacom Group again acting in concert (this time with Waterland) to acquire "certain business divisions" of Gamma if a deal proceeded. Multiple press reports since the Epiris recommendation (including Private Equity Wire and Global Banking & Finance) suggest Waterland is considering coming back with a bid higher than Epiris's. But as of 7 September 2026, Waterland has not announced a firm offer, and no price or terms for any Waterland bid have been disclosed or confirmed by a primary source. Waterland's own PUSU deadline is 5pm on 18 September 2026, so this remains a live, unresolved situation that could still change the outcome of this deal.
The Financing Angle
The cash consideration is being funded through a mix of equity and debt. On the equity side, Epiris's own funds are being supported by co-investment commitments from HarbourVest Partners and Limewood Capital, alongside Ares-managed funds as an equity co-investor. Ares funds are also providing debt financing to Bidco under an interim facilities agreement (full financing details are expected to be set out later in the scheme document). Goldman Sachs International, acting as exclusive financial adviser to Epiris and Bidco, has confirmed under the Takeover Code that sufficient cash resources are available to Bidco to meet the cash consideration in full. On Gamma's side, the board's financial advice came from Barclays (lead financial adviser, and the adviser giving formal independent "fair and reasonable" advice under Rule 3 of the Takeover Code) and Q Advisors, with Investec and Peel Hunt acting as joint financial advisers and joint brokers.
Latham & Watkins (London) LLP is confirmed as legal adviser to Epiris and Bidco. Bird & Bird LLP is the confirmed legal adviser to Gamma Communications.
Why It Matters
This is another entry in what's been a record year for UK public-to-private activity. UK takeover bids have reportedly passed the $100 billion mark for 2026 as private equity continues to find London-listed technology and services companies attractively priced relative to US or European peers. For students, it's also a useful live case study in the mechanics of a contested UK sale process: multiple PUSU cycles, bidders dropping out, a board ultimately recommending one offer, and, unusually, a credible prospect of a topping bid emerging even after a recommendation has been announced. It's a good reminder that a "recommended offer" is not the same thing as a completed deal.
Real-World Impact
If you've ever called a small business and the call routed through a cloud phone system, or your office uses Microsoft Teams for calls rather than a physical phone, there's a chance Gamma's technology was involved somewhere in the background, most people who rely on it don't know its name because it mostly sells to and through other businesses, not directly to the public. A change of ownership here is unlikely to be visible to end users immediately, but it's worth watching two things. First, Epiris has said it wants to "accelerate" investment in product development and AI as a private company, which is the kind of promise PE buyers usually make and which could mean either faster improvements or, if margins get squeezed post-buyout, cost discipline that affects service quality or jobs. Neither outcome is confirmed either way at this stage. Second, if Waterland's rival approach were ever to succeed instead, its structure would reportedly involve carving out "certain business divisions" of Gamma, said in some press reports to represent close to 30% of the company's revenue, and selling them separately to Giacom, which would be a more disruptive outcome for the employees and customers of whichever parts of the business moved. That carve-out scenario is currently speculative.