Veritas Capital's £1.65bn recommended acquisition of Bodycote plc
Hussain Jeddy · 3 September 2026
Share on LinkedInOn 1 September 2026, Bodycote plc, the world's largest provider of heat treatment and specialist thermal processing services, agreed to be acquired by US private equity firm Veritas Capital, in a recommended cash deal valuing the company at approximately £1.85bn on an enterprise value basis. Bodycote shareholders will receive 940 pence per share in total, made up of 932.8p in cash plus a 7.2p dividend they get to keep on top.
The Parties
Bodycote operates around 130 facilities across 22 countries with roughly 4,000 employees, providing thermal processing (heat treatment) that improves the durability and performance of metal components for aerospace, automotive, energy and industrial customers. Veritas Capital is a New York-based private investment firm founded in 1992 with roughly $54bn in assets under management, specialising in complex, regulated sectors. It already owns aerospace and defence names like Chromalloy and StandardAero, which is why Bodycote's aerospace-heavy customer base was a clear strategic fit.
Structure and Process
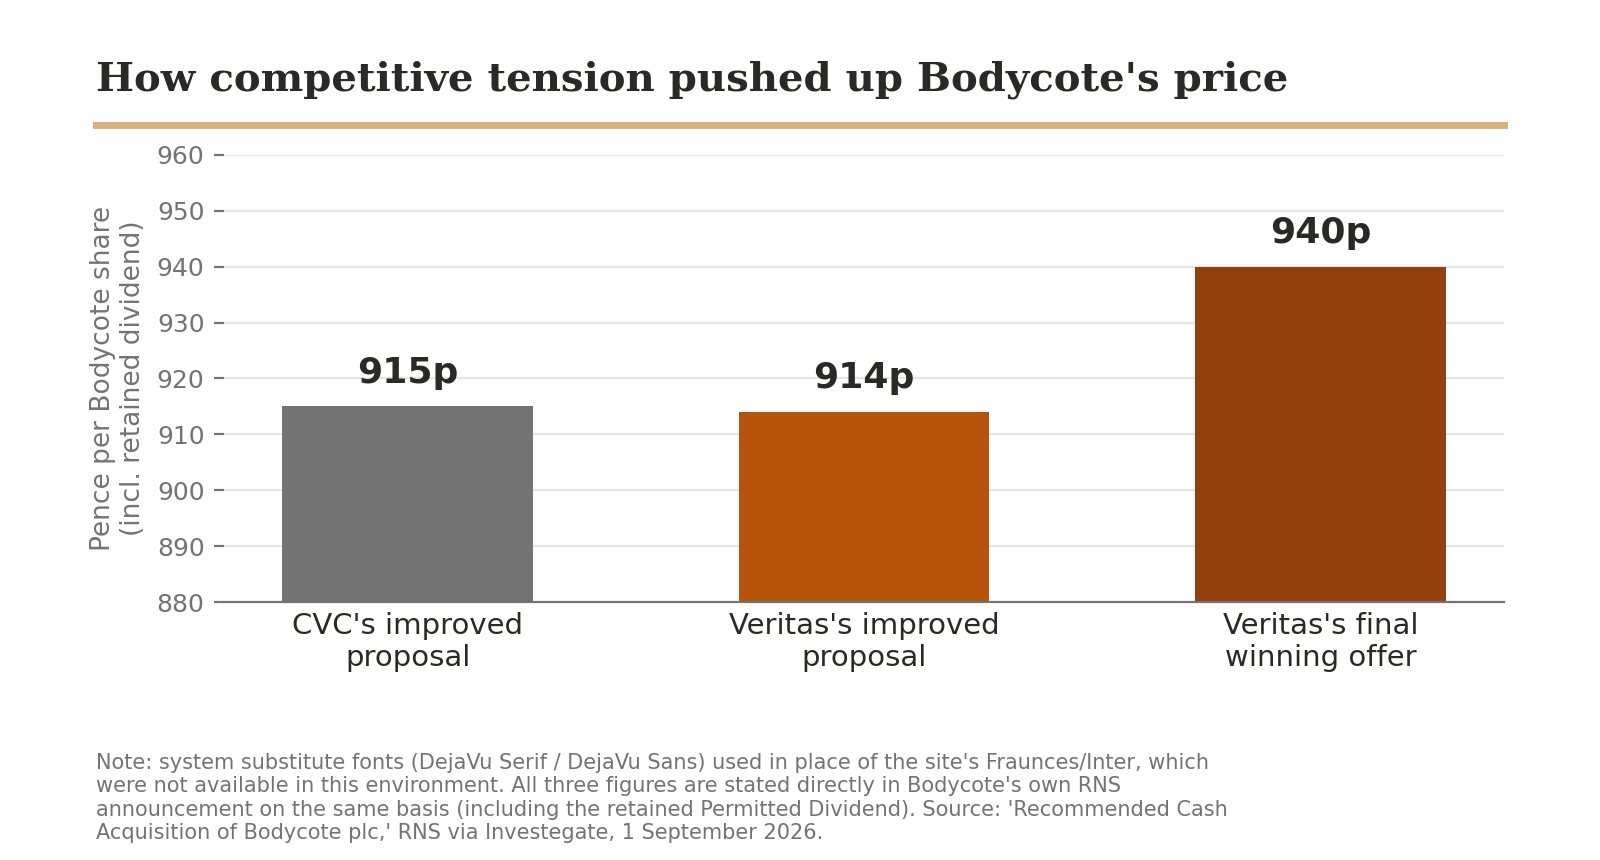
This was a competitive process. Apollo first made an unsolicited approach in May 2026. Bodycote's board then received separate competing proposals from both Veritas and CVC, running parallel negotiations with each rather than picking a single bidder upfront. This is an approach sometimes called a "beauty parade." Veritas's final improved bid of 940p edged out CVC's, and the deal will be implemented by a scheme of arrangement (a UK court-approved procedure, under Part 26 of the Companies Act 2006, that lets a bidder buy every share in one step once enough shareholders vote yes, as opposed to a contractual offer that shareholders accept individually one by one).
The Financing Angle
There is no information yet on Veritas's debt/equity financing split for this deal specifically, though as a $54bn private equity firm operating through its "core" buyout strategy, a mix of fund equity and acquisition debt is standard for a deal of this size. This detail should become clearer in the Scheme Document once published.
The financial advisers listed are Lazard for Veritas, and Barclays, Goldman Sachs, Jefferies and Gleacher Shacklock for Bodycote. The legal counsel is Gibson Dunn & Crutcher UK LLP for Veritas, and Herbert Smith Freehills Kramer LLP for Bodycote.
Why it matters
This is a good example of a UK-listed industrial company fielding competing private equity bids rather than negotiating with just one. Bodycote's board kept both Veritas and CVC in play simultaneously via separate, independent negotiating tracks, using the competitive tension to push the price up through several rounds of improved proposals before Veritas's offer won out.
Real-World Impact
Bodycote's thermal-processing work is involved with aircraft engines, cars, and industrial equipment most people never think about. Its heat treatment makes metal parts stronger and more reliable, including for aerospace and defence customers. With around 4,000 employees across 22 countries, a change of ownership here is more about long-term strategic direction (Veritas has a track record of investing further in its industrial portfolio companies) than about any announced job losses.