Banco Santander acquires Webster Financial Corp. for an implied equity value of $12.2bn
Hussain Jeddy · 23 August 2026
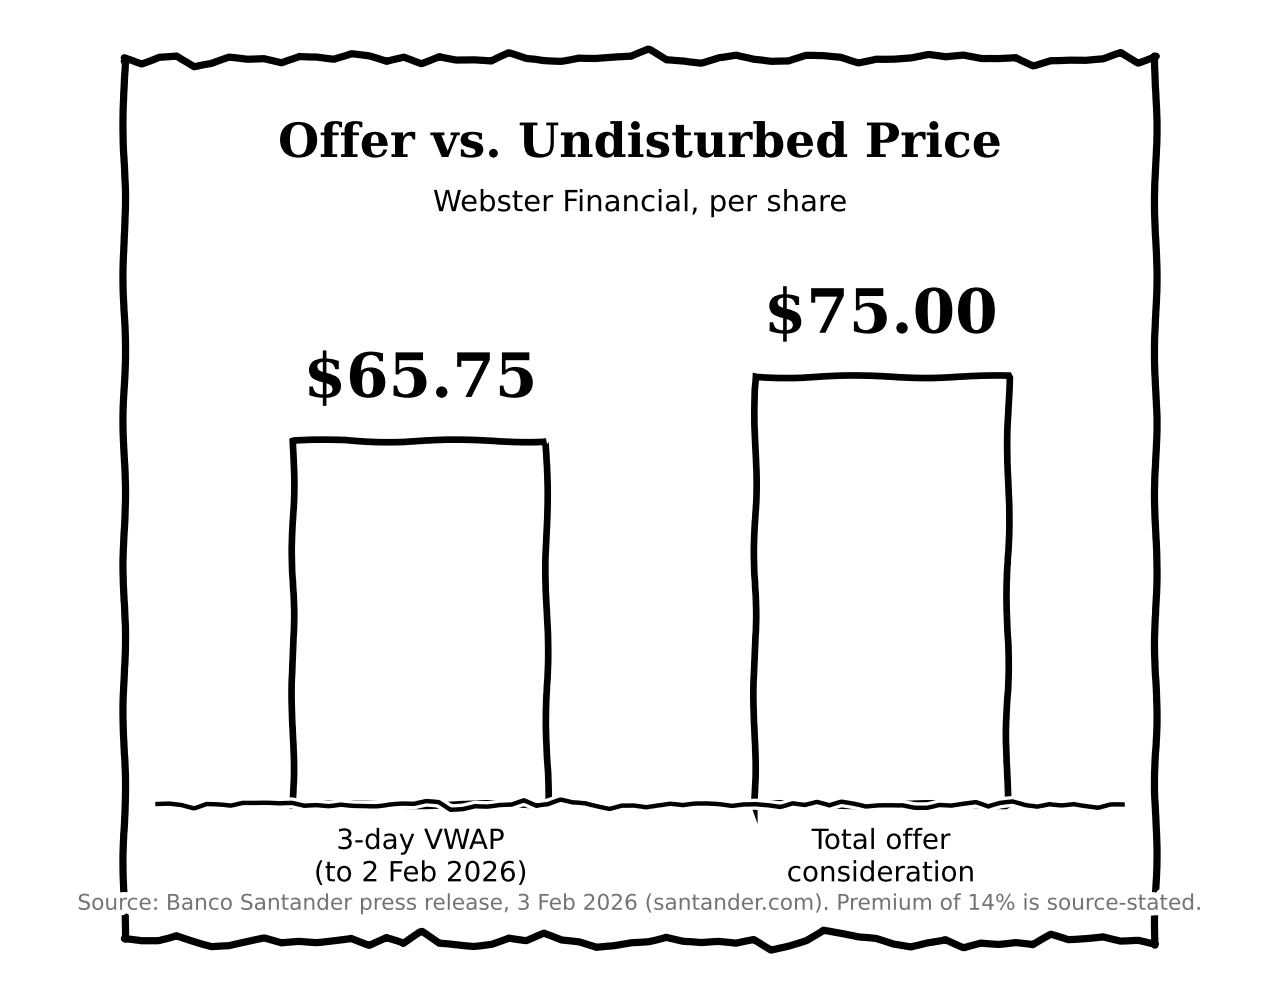
Share on LinkedInOn 20 August 2026, Banco Santander completed its acquisition of Webster Financial Corporation, the Stamford, Connecticut-based holding company for Webster Bank, N.A, in a deal first agreed on 3 February 2026. Webster shareholders received $48.75 in cash plus 2.0548 Santander shares in the form of ADSs (American Depositary Shares, which are the certificates that let a foreign company's shares trade on a US exchange) for every Webster share, a total of $75.00 per share, valuing Webster at an implied equity value of $12.2bn.
Santander is a Spanish multinational bank founded in 1857, with roughly €1.5 trillion in total funds, more than 182 million customers, and 6,500 branches worldwide as of mid-2026. Webster, founded in 1935, is a $80bn-plus-asset regional bank serving business and individuals across three lines: Commercial Banking, Healthcare Financial Services, and Consumer Banking, with its core footprint running from the New York metropolitan area up through Rhode Island and Massachusetts.
This was a negotiated bank holding company acquisition (a takeover of the parent company that owns a regulated bank, rather than a purchase of the bank's assets directly), carried out through a transaction agreement and a wholly-owned merger subsidiary. Because Webster Bank is a US-regulated depository institution and Santander is a foreign banking organisation, the deal needed sign-off from three separate regulators before it could close. These include the Office of the Comptroller of the Currency (approved 12 June 2026), the European Central Bank (authorised 21 July 2026, since Santander itself is ECB-supervised), and the US Federal Reserve (approved 4 August 2026). Santander and Webster shareholders also had to approve the deal. It closed on 20 August 2026, a little over six months after signing.
The consideration was split 65% cash and 35% newly issues Santander shares (delivered as ADSs, or as ordinary Santander shares where practicable). Santander described the transaction as self-funded through its own excess and future capital generation. There is no disclosed external debt financing package. Santander expects roughly $800m in annual cost synergies once the two US operations are integrated.
Davis Polk & Wardwell LLP are the US legal adviser to Santander, while Uría Menéndez is the Spanish legal adviser to Santander. Wachtell, Lipton, Rosen & Katz LLP is the legal adviser to Webster. On the financial side, Centerview Partners, Goldman Sachs and Bank of America Europe DAC are the financial advisers to Santander, while J.P. Morgan Securities LLC and Piper Sandler & Co. are the financial advisers to Webster.
This is one of the largest cross-border acquisitions of a US bank in years, and it reshapes the US regional banking landscape: the combined Santander-Webster business becomes a top-ten US retail and commercial bank by assets and a top five deposit franchise in the Northeast, with roughly $327bn in combined assets. For Santander, it is a deliberate 'bolt on', equivalent to only about 4% of the group's total assets, that nonetheless meaningfully upgrades its US funding profile by pairing its own consumer-finance-heavy US business with Webster's stronger, cheaper, commercial deposit base.