Madison Air Solutions Corporation agree to acquire ebm-papst for $5.4bn
Hussain Jeddy · 20 August 2026
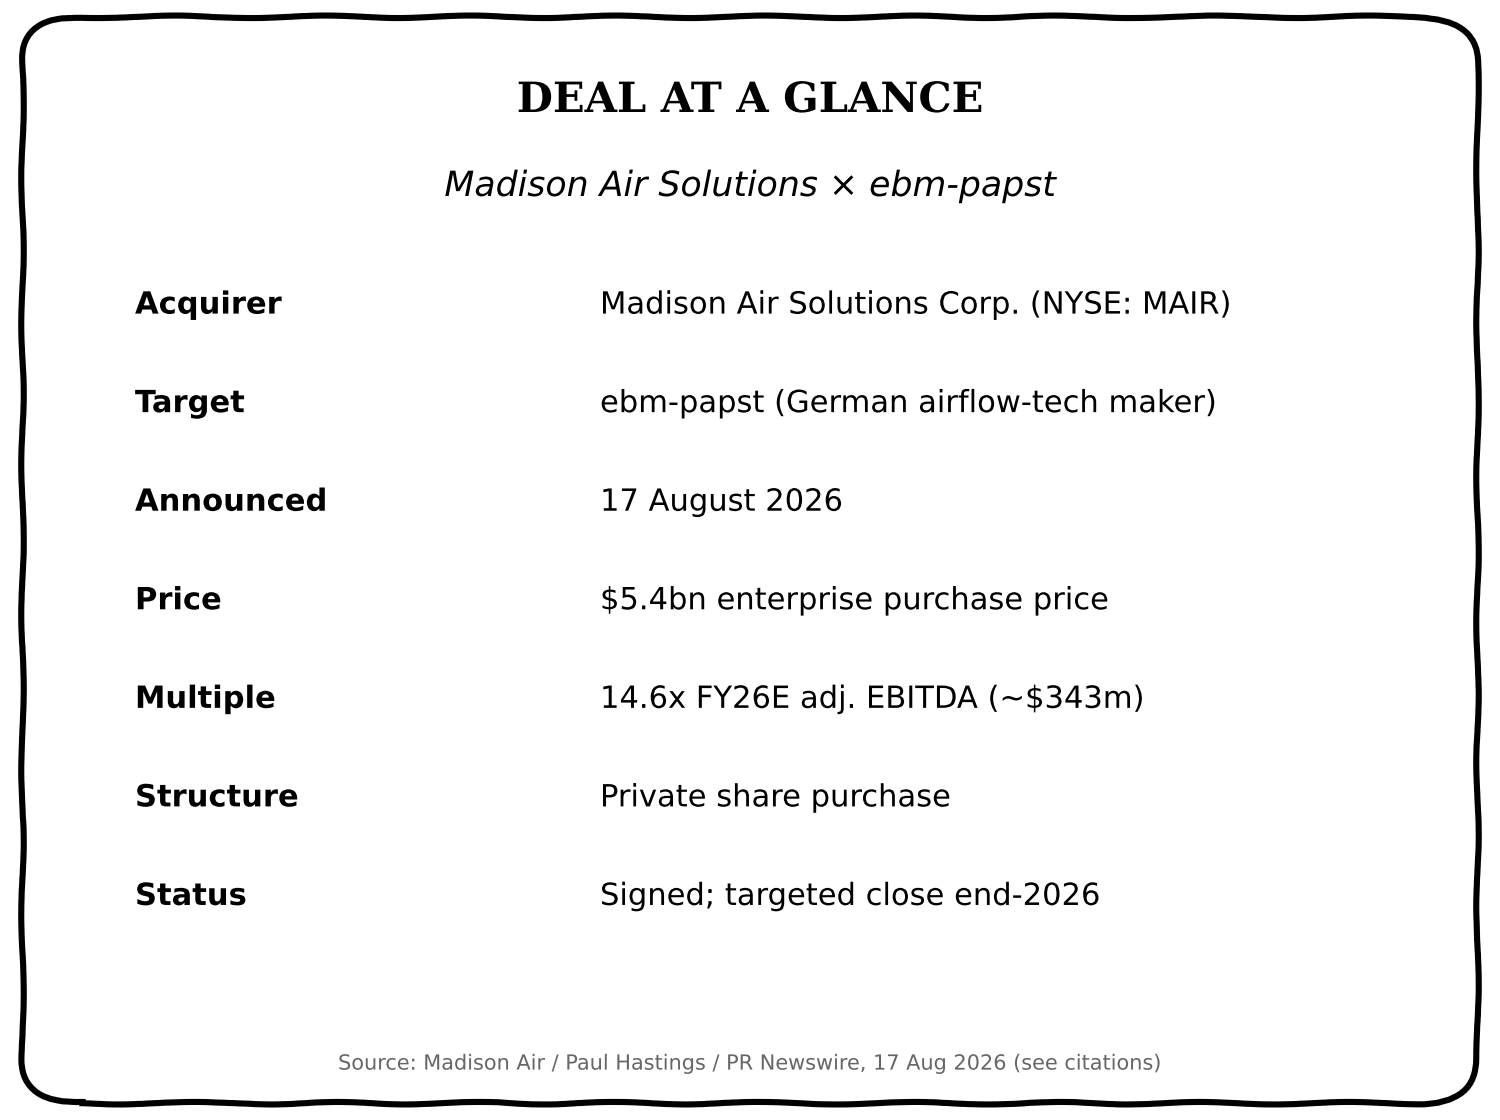
Share on LinkedInOn 17 August 2026, Madison Air Solutions Corporation, a US-listed provider of air quality solutions, agreed to acquire ebm-papst, a family-owned German airflow-technology manufacturer, at an enterprise purchase price of $5.4bn, around $5.0bn once expected future tax savings are netted off.
ebm-papst makes fans and electronically commutated motor systems, which are the kind of components that keep air moving through data centres, HVAC systems, and industrial equipment. It has more than 250 million of its fans installed worldwide, operates in roughly 40 countries, and is forecast to generate about $2.8bn of revenue in 2026. Madison Air Solutions describes itself as a global provider of air quality solutions, and appears to sit within the broader Madison Industries group of industrial and filtration businesses.
This is a private share purchase (an acquisition of a company's shares directly from it's owners, as opposed to buying specific assets). Madison Air is buying ebm-papst directly from the founding shareholder families, rather than through a public takeover bid, since ebm-papst is privately held.
The deal required coordinated US and German legal teams since the target is a German company being bought by a US-listed acquirer. Paul Hastings and Hengeler Mueller acted for Madison Air Solutions, while Milbank acted for ebm-papst. Reports suggest the whole negotiation was completed in roughly ten weeks. Completion is subject to customary regulatory approvals and is targeted for the end of 2026.
Madison Air has received a debt commitment letter covering the acquisition financing, with fully underwritten commitments from UniCredit and Wells Fargo (the banks have committed to provide the full specified financing themselves, even if they later intend to sell portions of the debt to other lenders). Madison Air also expects to realise $160m in annual run-rate cost synergies by the third year after closing, which is presumably part of the underlying investment case even if it isn't 'financing' in a strict sense. This means by year three, Madison Air expects the combined businesses to have reduced recurring annual costs by about $160m, for example by eliminating duplicated functions or achieving procurement savings. Those savings help justify the price Madison Air is paying because they should increase the combined company's future profitability and cash flow.
The deal roughly doubles Madison Air's addressable market by about $30bn, extending it into ebm-papst's commercial, aftermarket and services opportunities, with an explicit shift to the boom in data-centre cooing demand as a growth driver for airflow technology. It is also an example of how quickly a cross-border private deal can move when both sides commit specialist local counsel in each jurisdiction from the outset.
Update — 25 August 2026
Deal terms are unchanged, but Madison Air's own share price has fallen roughly 27% in the week since the $5.4bn acquisition was announced on 17 August 2026, as investors focus on how the deal's cash-debt-and-new-equity funding mix will affect leverage and existing shareholders' dilution. Several analysts trimmed price targets even as Madison Air's underlying business reported strong quarterly results.
This matters because no financing condition applies to the deal, and lenders have reportedly committed funding, so this is a market-confidence overhang rather than a change to the deal's legal terms. But the dilution question is now the dominant unresolved variable in how the market is pricing the transaction, alongside the antitrust and foreign-investment clearances the deal already requires.